Commercial Mortgages Southampton
We are a commercial mortgage broker in Southampton, arranging owner-occupier, investment, semi-commercial, portfolio and trading-business mortgages across the city, the Solent and Hampshire. We approach the high-street, challenger and specialist lenders whose criteria fit your deal, with indicative terms usually within 48 hours. We are not authorised by the FCA and arrange unregulated commercial finance only.
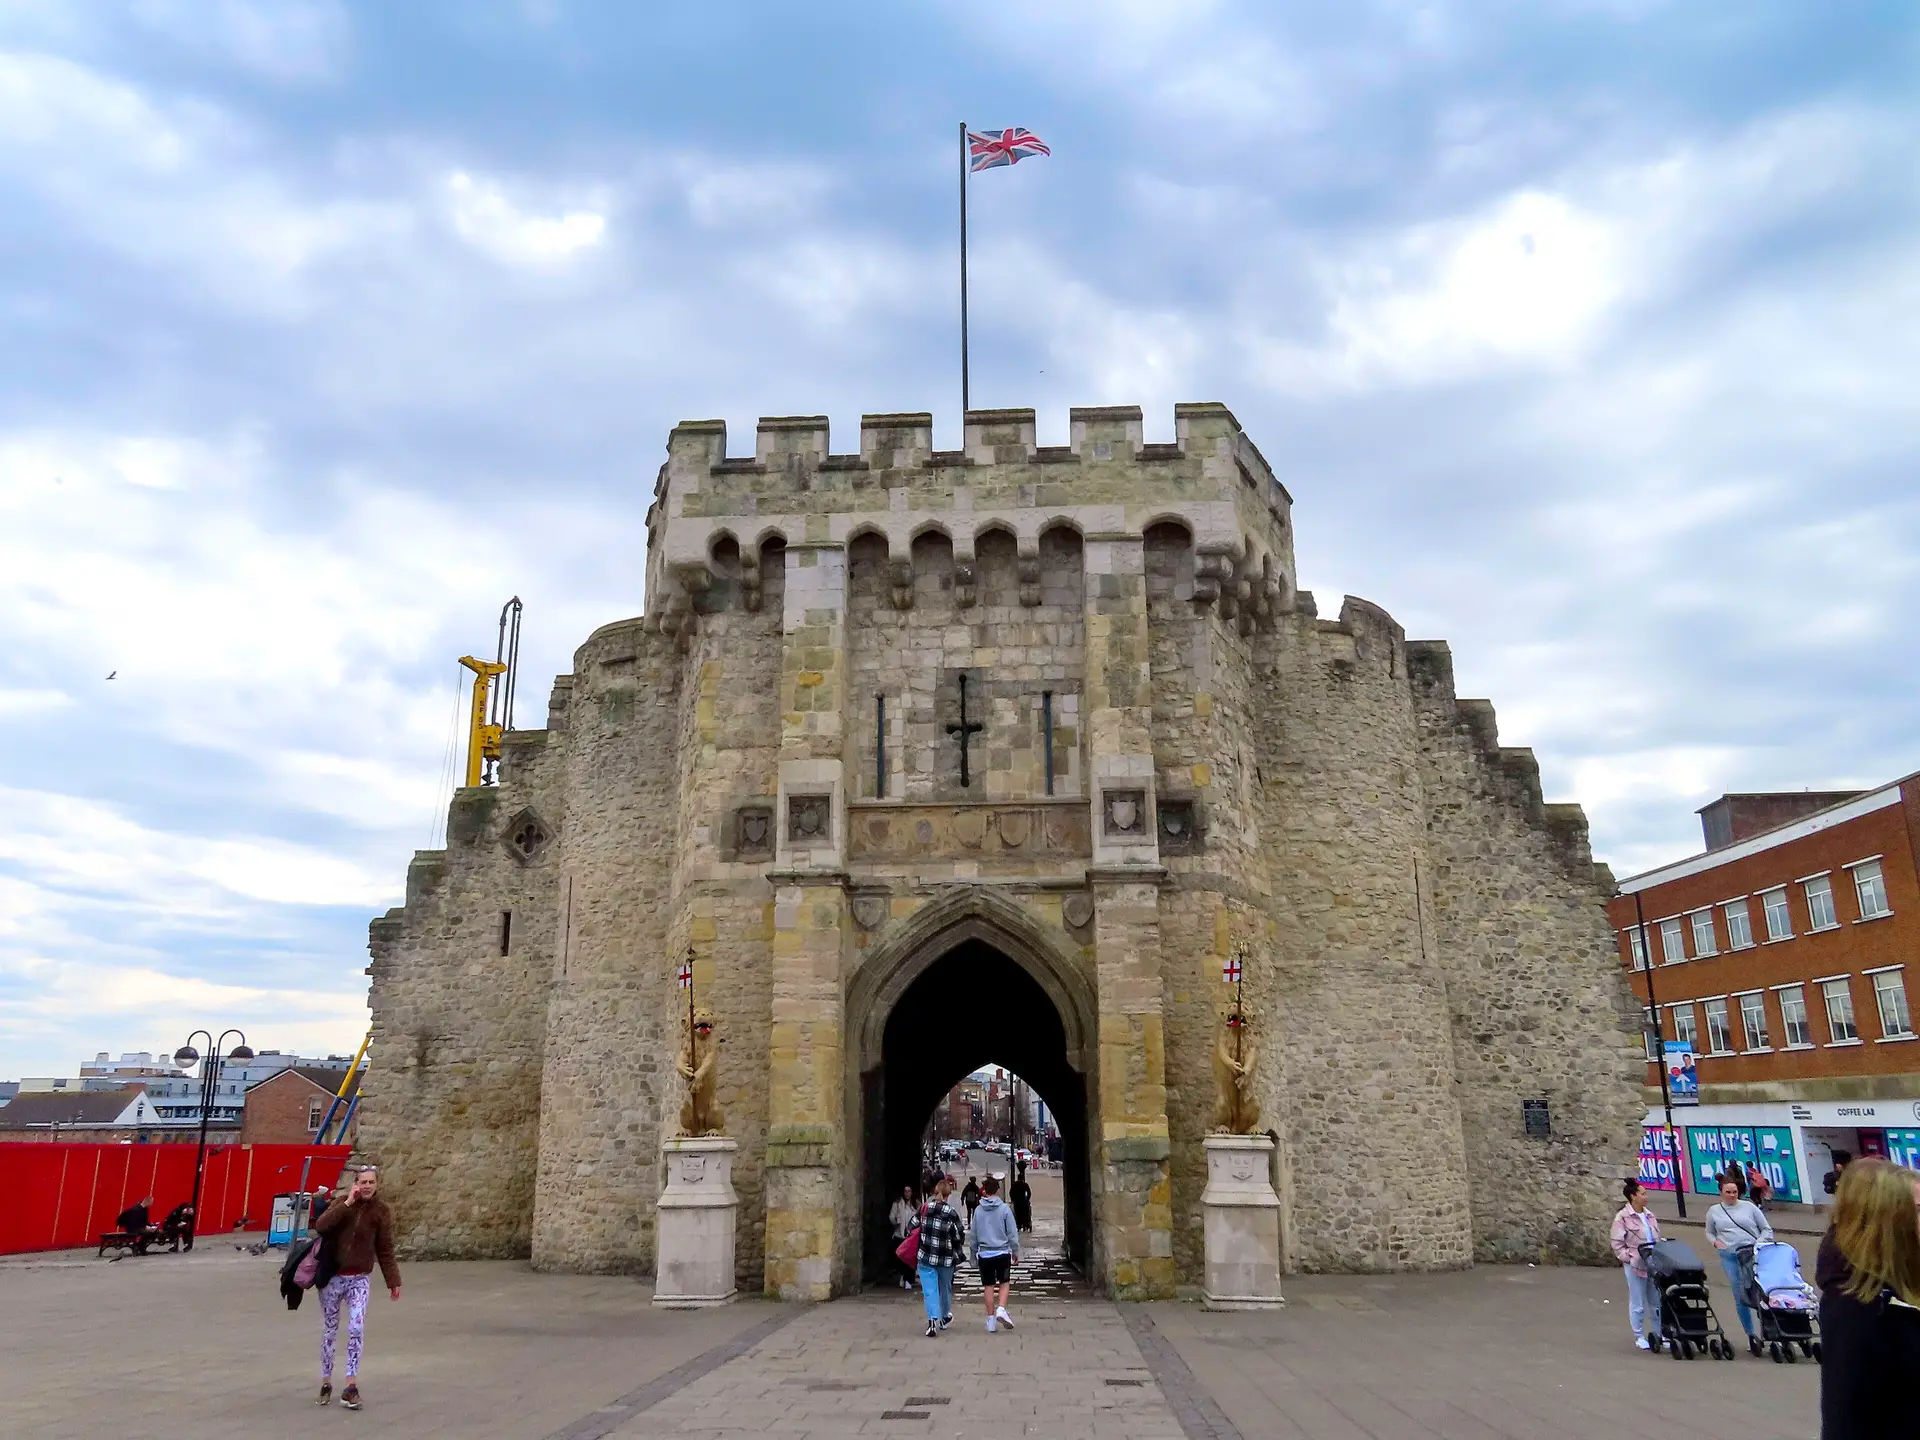
The Bargate, Southampton
Property finance arranged
Years in financial services
Indicative terms
Typical max LTV
The market, in numbers.
Mid-2026 Southampton CM market, Indicative market pricing
90+
Lender market
High-street, challenger and specialist desks
48hr
Indicative terms
From complete enquiry
£400M+
Arranged
Across the network
75%
Max LTV
Owner-occupier and investment
Most commercial mortgages in Southampton come down to one of three conversations, owner-occupier, commercial investment, or trading-business finance.
1. Owner-occupier: buying the business premises your business trades from. The dental partnership taking the Lordswood SO16 surgery freehold off a retiring principal in the University Hospital Southampton healthcare belt across Bassett and Lordswood. The accountancy practice converting a lease-end into a Cumberland Place SO15 townhouse purchase. The freight forwarder taking its own warehouse at Adanac Park SO16 off the M271 logistics spine. The light-industrial trade-counter buying its Nursling SO16 unit off the landlord. Underwriting for owner-occupier commercial mortgages hinges on filed accounts and EBITDA cover, typically 1.3 to 1.5 times the monthly mortgage payment, sometimes lower for established healthcare and professional-services sectors. Maximum loan-to-value to 75% on bricks-and-mortar, term 5 to 25 years. Allica Bank, Shawbrook, Hampshire Trust Bank and Cambridge & Counties Bank sit at the sweet spot for the owner-occupied mortgage in Southampton. Lloyds, NatWest and Barclays price competitively for the owner-occupier borrower where the covenant is strong and the sector is mainstream. Real mid-2026 Southampton rates for owner-occupier: 6.0 to 7.5% pa. See owner-occupier commercial mortgages in Southampton.
2. Investment landlord: buying or refinancing a let commercial property. Acquiring a Westquay SO15 retail unit on a 10-year FRI lease to a national covenant. Refinancing four Highfield and Portswood SO17 HMO blocks let to University of Southampton and Solent University students off a maturing 5-year fix. Adding asset eight to a 6 million pound Above Bar Street and Bargate Quarter prime-retail investment portfolio. A commercial investment mortgage tests rental cover on the rental income, not your personal income. Typically ICR 140 to 160% on prime investment, DSCR 130 to 145% on portfolio. Lease length and tenant covenant carry as much weight as LTV, and in Southampton the Carnival UK (Ocean Village), Associated British Ports (Western Docks) and University Hospital Southampton NHS Foundation Trust occupier covenant chain underwrites a meaningful share of the prime office and industrial investment stock. NatWest, Lloyds, Barclays and Santander all compete on prime single-asset commercial investment mortgages in Southampton. InterBay Commercial, LendInvest, Paragon and Together sit at the trickier end of investing in commercial property and HMO blocks (multi-let, short lease, semi-commercial, student-let). Rate range for the commercial investment mortgage: 6.5 to 8.5% pa. See commercial investment mortgages or portfolio refinance. For the wider local market read see our editorial on the Southampton commercial property market in 2026, or visit our Southampton commercial mortgage broker hub.
3. Trading business: owner-operator buying a going concern. The freehold marina hotel off Ocean Village SO14 on the cruise-tourism passenger flow that runs around 3 million passengers a year through the ABP cruise terminals. The CQC-rated care home off the University Hospital Southampton ancillary belt in Bassett and Lordswood. The boutique B&B off Above Bar Street SO14. The independent restaurant on Bedford Place, The Polygon SO15. The neighbourhood pub on Portswood Road, Portswood SO17. These are sector-specialist commercial mortgage applications. Lenders weigh goodwill, barrelage, room counts and RevPAR, CQC ratings, occupancy and Ofsted alongside bricks-and-mortar value. Southampton cruise-tourism passenger flow through the ABP terminals plus the Carnival UK HQ at Ocean Village sustains the hospitality book at the marina end of the city, while two universities driving roughly 34,000 students between them anchor the F&B and HMO trading-business book across Bevois Valley and Highfield. EBITDA cover 1.5 to 2.0 times. LTV typically 60 to 70% on bricks, sometimes 70%-plus where goodwill is strong and the trading covenant is well evidenced. Allica Bank, Shawbrook, Cambridge & Counties Bank and Hampshire Trust Bank dominate this segment of business mortgage and business loan demand in Southampton. Cynergy Bank is particularly active on hospitality across the South Coast, alongside Allied Irish Bank (UK) and Metro Bank for hotel deals. Rate range: 7.0 to 9.0% pa. See trading-business commercial mortgages.
The commercial mortgage range, with the numbers.
Indicative ranges from live lender positions across the market as of mid‑2026. LTV, cover and rate move per asset class, lease quality and trading covenant; these are the typical bands.
| Product | Facility | LTV | Cover test | Rate (pa) | Term |
|---|---|---|---|---|---|
| Owner-occupier Trading business buying its own premises. Underwritten on filed accounts and EBITDA cover, not personal income. | £150K - £10M | up to 75% | EBITDA 1.3-1.5× | 6.0 - 7.5% | 5 - 25y |
| Commercial investment Buying or refinancing a let commercial asset. Driven by rental income, lease length and tenant covenant, not your own job. | £200K - £10M | up to 75% | ICR 140-160% | 6.5 - 8.5% | 5 - 25y |
| Semi-commercial Mixed-use including shop with flats above, restaurant with private accommodation, B&B with owner quarters. Specialist desks lead this. | £150K - £5M | up to 75% | DSCR 130-145% | 6.5 - 8.5% | 5 - 25y |
| Portfolio refinance 5+ commercial assets, single facility, blended LTV. Restructures a maturing facility or rolls up multiple loans. | £500K - £25M | up to 70% | Blended ICR 140% | 6.5 - 8.0% | 5 - 25y |
| Trading business Pubs, hotels, care homes, dental, MOT, nurseries, vets, B&B. Sector specialists assess goodwill, barrelage, occupancy, CQC ratings. | £150K - £5M | 60 - 70% | EBITDA 1.5-2.0× | 7.0 - 9.0% | 10 - 25y |
| Commercial remortgage Refinancing an existing commercial mortgage on better terms, raising capital, or exiting an ERC window with a 5-year fix. | £150K - £10M | up to 75% | ICR/DSCR 140%+ | 6.0 - 8.0% | 5 - 25y |
| Commercial bridging Short-term to permanent. Bridges auction completion, vacant-to-tenanted, or unmortgageable-to-mortgageable, with a term CM exit. | £150K - £5M | up to 70% | Interest-only | 8.5 - 11.0% | 6 - 24m |
| Second-charge Capital raise behind an existing first charge. Useful when the first charge is at a low rate you don't want to disturb. | £100K - £2M | combined 75% | DSCR 130%+ | 8.5 - 11.0% | 5 - 15y |
Trading business buying its own premises. Underwritten on filed accounts and EBITDA cover, not personal income.
Facility
£150K - £10M
LTV
up to 75%
Cover
EBITDA 1.3-1.5×
Rate
6.0 - 7.5%
Buying or refinancing a let commercial asset. Driven by rental income, lease length and tenant covenant, not your own job.
Facility
£200K - £10M
LTV
up to 75%
Cover
ICR 140-160%
Rate
6.5 - 8.5%
Mixed-use including shop with flats above, restaurant with private accommodation, B&B with owner quarters. Specialist desks lead this.
Facility
£150K - £5M
LTV
up to 75%
Cover
DSCR 130-145%
Rate
6.5 - 8.5%
5+ commercial assets, single facility, blended LTV. Restructures a maturing facility or rolls up multiple loans.
Facility
£500K - £25M
LTV
up to 70%
Cover
Blended ICR 140%
Rate
6.5 - 8.0%
Pubs, hotels, care homes, dental, MOT, nurseries, vets, B&B. Sector specialists assess goodwill, barrelage, occupancy, CQC ratings.
Facility
£150K - £5M
LTV
60 - 70%
Cover
EBITDA 1.5-2.0×
Rate
7.0 - 9.0%
Refinancing an existing commercial mortgage on better terms, raising capital, or exiting an ERC window with a 5-year fix.
Facility
£150K - £10M
LTV
up to 75%
Cover
ICR/DSCR 140%+
Rate
6.0 - 8.0%
Short-term to permanent. Bridges auction completion, vacant-to-tenanted, or unmortgageable-to-mortgageable, with a term CM exit.
Facility
£150K - £5M
LTV
up to 70%
Cover
Interest-only
Rate
8.5 - 11.0%
Capital raise behind an existing first charge. Useful when the first charge is at a low rate you don't want to disturb.
Facility
£100K - £2M
LTV
combined 75%
Cover
DSCR 130%+
Rate
8.5 - 11.0%
Compare commercial mortgage solutions in Southampton: available lenders and interest rates, commercial investment mortgage, owner-occupier commercial mortgages, and the commercial mortgage journey.
What a commercial mortgage is. A commercial mortgage is a long-term commercial loan secured against a non-residential property in the United Kingdom used for business purposes, the cornerstone of real estate investing and commercial property finance. The property itself sits as security for the loan: if the borrower (the debtor) does not repay, the lender (the creditor) can repossess and recover the debt against the asset value under the rules on default (finance). That principle is the same as a standard residential mortgage, but the underwriting is different. A standard residential mortgage tests personal income and FCA-regulated affordability. A commercial mortgage in Southampton tests the business premises, the trading business inside it, and the rental income or lease income from any leasehold estate let inside the building. Commercial mortgages on non-dwelling commercial properties fall outside the FCA regulated mortgage perimeter, so this product is not regulated by the Financial Conduct Authority. We are not authorised and regulated by the FCA because the products we arrange are unregulated; in the financial services market this is called unregulated commercial lending. Where a deal would require FCA authorisation we refer the enquiry to a firm authorised and regulated for the relevant residential or commercial product. We act as a credit broker, not a lender, sourcing commercial finance for Southampton business owners and property investors, with the loan amount and loan-to-value ratio modelled deal-by-deal across our range of commercial lenders.
The four core deal types we see across Southampton, the Solent and Hampshire. Owner-occupied commercial mortgages: a trading business buys the business premises it operates from, dental, accountancy, creative agency, light-industrial, Class E retail, an Above Bar Street SO14 professional-office suite, a freight-forwarding unit at Adanac Park or Nursling SO16 off the M271 logistics spine, or a Hedge End SO30 trade-counter. Repayments on your mortgage come from EBITDA, so lenders model 1.3 to 1.5 times trading-profit cover on the owner-occupied mortgage. The owner-occupied route is the standard product available for Southampton SMEs buying a commercial property to trade from. Commercial investment mortgage: an investment property let to third-party tenants on commercial leases, tested on rental cover (ICR 140 to 160%) rather than your personal income. Most property investors choose this investment commercial mortgage route for let commercial property and existing commercial property held as a leasehold estate inside a limited company or SPV (ltd structure for tax). Limited companies dominate the investment commercial mortgage book on the Southampton side, with a single SPV per asset on stretched LTV deals. Semi-commercial mortgages: the classic flat above a shop on Portswood Road, Shirley High Street, Above Bar Street or Bitterne Triangle, blended retail and residential income in mixed-use properties, 70 to 75% LTV on the strong shop-and-flat archetype. Trading-business mortgages: a marina hotel at Ocean Village, B&B, pub, restaurant, care home, MOT garage or day nursery bought as a going concern, where goodwill and sector ratings (CQC, Ofsted, RevPAR) shape the deal alongside bricks-and-mortar value. None of this overlaps with buy to let mortgages, which are a residential mortgage product tested on personal income and rental yield. A residential buy-to-let mortgage sits with a different pool of buy-to-let commercial lenders. We focus on commercial mortgage applications on existing commercial property and on property to let for business use.
What drives commercial mortgage rates in Southampton. The loan-to-value ratio (LTV) is the lever. Owner-occupier reaches 75% on bricks-and-mortar property value, semi-commercial 70 to 75%, trading-business hotel 60 to 70%. Lender appetite, lending criteria and property value are confirmed by a RICS Red Book property valuation (a real estate appraisal) commissioned before the binding mortgage offer. DSCR (debt-service coverage ratio) tests net rental income against the full mortgage repayments on a commercial investment mortgage, typically at 130 to 145%. ICR (interest cover ratio) tests rent against the interest payments component at 140 to 160%. The Bank of England base rate trajectory and the gilt curve set lender funding costs, then individual commercial lenders price margin on top. Mid-2026 Southampton commercial mortgage rates: 6.0 to 7.5% pa on owner-occupier, 6.5 to 8.5% pa on commercial investment and semi-commercial, 7.0 to 9.0% pa on trading-business hotel and hospitality. Five-year fixes price roughly 0.25 to 0.50% above two-year fixes on the fixed rate side, with fixed and variable rate commercial mortgages running alongside each other for any fixed period 2 to 10 years. Bridging finance for change-of-use, auction purchases, or chain-break funding sits at 0.75 to 1.10% pm. When clients search for a bridging loan in Southampton we route the deal to a different set of commercial lenders: the bridge market is a higher-risk specialist area with its own products available and its own appetite. A bridge can run six to 24 months on rolled-up interest, with the bridge exit either a sale or a refinance to a term commercial mortgage. Bridging finance examples we see weekly include an Above Bar Street retail-to-Class E hospitality bridge, an Ocean Village marina refurb-bridge, and a Nursling industrial bridge for trade-counter conversion off the M271, typical loan amounts from 500K to 5M pounds. Interest-only structures are available on most commercial investment mortgage deals across the market, supporting cash flow on let property to let stock like retail units, mixed-use parade, care homes and HMOs renting to students across the SO14, SO15, SO16 and SO17 belt. Interest-only on owner-occupier is rarer, lenders prefer capital and interest on owner-occupier so the loan amortises against the trading business, but a part interest-only and part repayment structure is possible. The interest-only window on most investment products runs five to ten years before the lender reviews. Lenders weigh credit score, business banking history, and the property local market on every deal.
Refinance, remortgage, capital raise and business growth. Around a third of the deals we run for Southampton clients are not a fresh purchase commercial property transaction at all. They are a refinance or commercial remortgage off a maturing fix, capital raise to release equity against rising asset value to fund business growth, or release on sale of part of a property portfolio. M271 and M27 corridor industrial supply is tight and Hampshire-wide industrial yields read tighter than the Southampton-only data suggests because lenders price the corridor not the city, so refinance and equity release dominate flow on the prime warehouse and trade-counter stock around Adanac Park, Nursling and the Hedge End business park flank. The same lenders and the same metrics apply: LTV, DSCR, ICR, EBITDA, lease length, tenant covenant, affordability. Competitive rates on commercial funding are most readily available on prime owner-occupier and prime investment, where high-street commercial desks compete hardest for the best deal and the best commercial mortgage offer. Stretched LTV, short-lease investment, HMO portfolio or sector-specialist trading business pushes the deal to a challenger or specialist commercial lender on a slightly higher margin, but the deal still completes. The auction purchases route, where speed kills the term option, runs via bridging finance first then a refinance to term once the asset is stabilised. Applying for a commercial mortgage in Southampton starts with a property pack, two years filed accounts (or rent roll for the investment commercial mortgage, occupancy and RevPAR for hotel), a one-page business plan, a clear sense of the deposit you can put in, and a clear sense of business needs and intended business use of the property.
Why use a commercial mortgage broker rather than going direct. The high street commercial desks price within their own credit policy and rarely compare their offers with other lenders. We compare the high-street, challenger and specialist lenders whose criteria fit the deal, every time. We are a credit broker and not a lender. We are not authorised or regulated by the Financial Conduct Authority and arrange non-regulated commercial finance only, working across a wide range of lenders rather than tying clients to one bank. For Southampton business owners choosing between two or three lenders direct, the spread between cheapest and most expensive viable mortgage offer is routinely 0.40 to 0.90% on rate plus 0.50 to 1.50% on arrangement fee, on a 1 million pound facility that compounds across the term. We map commercial mortgage solutions across the market and present every finance option and every product available, a full set of finance solutions and financial solutions for the deal: high street commercial banks, challenger banks, specialist lenders, hospitality-active commercial lenders, private finance, corporate finance for larger structured tickets, business loans secured against trading-asset value, development finance for property development, commercial developments and practically-complete Mayflower Quarter or Royal Pier Waterfront-adjacent development projects exiting senior dev debt, bridging loans and development finance where the timing demands it, and bridging finance for auction or chain-break. We arrange commercial mortgages, bridging loans and commercial mortgages for investors and business owners across Hampshire on commercial and mixed-use property, including commercial and residential mixed-use schemes, with finance and development packages structured around the deal. Our broker service on commercial deals starts with a free initial consultation, by phone or in person, on the Southampton 023 line. We will sit on the phone with a property investor weighing two letting routes, or a Southampton SME weighing freehold against lease renewal, and walk through the numbers without pushing a single lender. Whether the deal is an owner-occupier purchase, a commercial investment mortgage on a single let investment property, a portfolio refinance across a property portfolio, or a commercial mortgage refinance to reduce mortgage repayments off a maturing fix, we model it lender-by-lender first. As your commercial mortgage broker, we review the lenders whose criteria fit the deal and interest rates table, weigh the rates and terms, and shortlist three to five lenders for the best deal on the day. The broker fee is transparent and disclosed on completion, no upfront retainers. If the numbers will not work for any sensible commercial purposes or business use, we say so inside two business hours. Looking for a commercial mortgage that completes in four to eight weeks from application to completion? Most Southampton deals run in that window. The commercial mortgage journey is shorter when the borrower has a clean business plan, a clean credit history, and the lender has recent comparable approvals on file. As experts in commercial mortgages covering Southampton, the Solent, the M27 corridor and the wider Hampshire catchment, we structure every deal around your specific business needs and finance requirements with support from initial consultation through property valuation, commercial property transactions due diligence, solicitor instruction and completion of the transaction. Our Southampton 023 line is the fastest way to a same-day view on whether we can help, including referrals to regulated firms where the deal sits inside the FCA perimeter, and on whether your deal is regulated by the Financial Conduct Authority or sits outside the FCA perimeter.
The Southampton commercial property market in 2026, in numbers. Southampton is the Solent port-led commercial market, a city of around 250,000 people on the M27 and M3 spine with commercial property dominated by port-and-logistics, education-driven leisure and retail, and a regenerating central waterfront. Associated British Ports operates the Western Docks container terminal, the largest UK vehicle-handling port, and the ABP cruise terminals carry around 3 million passengers a year, which underwrites a meaningful share of the city hospitality book. Carnival UK is headquartered at Ocean Village SO14, alongside the marina-led hospitality cluster and a small office anchor. Westquay (Hammerson) anchors the flagship central retail spine across SO15 with around 800,000 square feet of retail; Above Bar Street, Bargate Quarter and the Royal Pier Waterfront feed into the wider central retail and leisure mix, while the Mayflower Quarter Watermark redevelopment is the live mixed-use regeneration scheme. The HMO market is one of the stronger student-led markets on the South Coast: University of Southampton with around 23,000 students and Solent University with around 11,000 together drive around 34,000 student-led HMO and PBSA demand, concentrated on Bevois Valley SO14 and Highfield and Portswood SO17, with Paragon, Together and Foundation Home Loans active on the HMO portfolio refinance book. University Hospital Southampton (NHS Foundation Trust) on the SO16 belt anchors a substantial private healthcare and care-home cluster including the Spire and Nuffield, driving steady owner-occupier freehold flow on dental, GP and allied health stock across Bassett, Lordswood and Bitterne. The industrial-warehouse base is the strongest of any of our cities: Adanac Park and Nursling Industrial Estate SO16 sit on the M271 logistics spine, with Ordnance Survey adjacent at Adanac and the M27 corridor sharing with Portsmouth as a single industrial labour shed, so Hampshire-wide industrial yields price tighter than the Southampton-only data suggests. Recent town-stats data shows a residential median around 249,000 pounds with a softer trend year-on-year, 2,407 residential transactions in the last twelve months, and 253 planning applications received with 79 commercial-mortgage-relevant and a 96% approval rate on those decided. For the commercial mortgages in Southampton market this means a structural bias toward industrial and logistics on the M271 and M27 corridor flank, cruise-tourism-led hospitality at Ocean Village and the waterfront, central retail and semi-commercial across Westquay and Above Bar Street, HMO-block refinance across the Bevois Valley, Highfield and Portswood student-let belt, and healthcare and care-home owner-occupier across the University Hospital Southampton flank.
Practical notes for Southampton business owners and property investors considering a commercial mortgage. Commercial mortgages typically run on a 3 to 25 years term, with capital and interest the default and interest-only available on most commercial investment mortgage deals. Commercial mortgages work differently to a standard residential mortgage: unlike residential mortgages, which the Financial Conduct Authority regulates, commercial mortgage products are unregulated and we operate as a commercial mortgage broker sourcing finance lender by lender. We arrange commercial mortgages and bridging finance to buy or refinance commercial property or land used for business purposes, including retail units, warehouse and industrial stock, mixed-use properties, semi-commercial parade, hospitality and care. Lenders offer different rates available depending on tenant covenant strength: prime national-covenant leases secure finance at competitive mortgage rates, while shorter leases or weaker tenants push deals to specialist commercial lenders at higher interest rates. We help property investors invest in commercial property, build property portfolios and service the debt against the rental income stream, with equity release at refinance where commercial property values have moved. The mortgage process for mortgages for commercial property in Southampton runs broadly the same as commercial mortgages in the UK more generally: we assess your financial standing, the type of loan that fits, model affordability, run the market and present mortgage products that secure finance on the day. The Southampton property and Southampton property finance market is one of the most diverse commercial markets on the South Coast, blending port-and-logistics industrial, central retail, marina hospitality, student-led HMO and a healthcare cluster, so we benchmark across the high-street, challenger and specialist lenders whose criteria fit the deal every time, including specialist commercial lenders for sector-specific cases like hotel, HMO and care, to get the best deal for the client and find the right mortgage. Lender indemnity insurance may be required on stretched LTV cases. Across our finance options we run owner-occupied mortgages, commercial investment mortgages, semi-commercial, portfolio refinance, business mortgages on trading-business stock, asset finance for vehicles and plant alongside the commercial mortgage where helpful, and bridging finance for time-sensitive deals; the finance providers in the market include high street banks, challenger banks and specialist lenders. Businesses in Southampton looking to buy to let property on a commercial basis or to secure funding for property investment in commercial stock get the same treatment, deal by deal, across the lenders whose criteria fit. Frequently asked questions on Southampton commercial mortgages are covered in the FAQs below.
The Southampton commercial lender market in 2026. A wide range of high-street, challenger and specialist lenders is active on Southampton stock, and we approach the lenders whose criteria fit the deal, deal by deal. Lloyds Commercial Banking, NatWest (Above Bar commercial team), Barclays, Santander Corporate and HSBC UK (Ocean Village business banking) cover the high street commercial book on prime owner-occupier and prime commercial investment, with NatWest and Lloyds the most relationship-active in central Southampton, though many Hampshire deals refer from the Portsmouth and Bournemouth regional desks. On the challenger and specialist commercial side, Shawbrook, InterBay Commercial, LendInvest and Cynergy Bank are among the most active commercial lenders in Southampton on industrial-logistics, hospitality, semi-commercial, multi-let HMO investment, trading-business and stretched-LTV cases on every type of commercial space across the city. Cynergy Bank in particular is highly active on hospitality and is one of the go-to desks for South Coast hotel refinance and acquisition. Allica Bank, Hampshire Trust Bank (HTB), Aldermore, YBS Commercial, OakNorth and Allied Irish Bank (UK) complete the high-street and challenger flank, with Allied Irish Bank (UK) and Metro Bank picking up the hotel and hospitality ticket alongside Cynergy. Paragon Bank, Together and Foundation Home Loans are very active on Southampton HMO portfolio refinance given the 34,000-student local market across University of Southampton and Solent University. Cambridge & Counties Bank is a defensible specialist on local owner-occupier, semi-commercial and trading-business deals across the Hampshire coast and the Solent flank. Private credit and fund finance (Octopus Real Estate, ASK Partners, Pluto Finance) sit on selected 5 million pound-plus Southampton waterfront, Mayflower Quarter or Royal Pier Waterfront-adjacent deals. Every commercial mortgage application we run starts with an assessment of which high-street, challenger and specialist lenders' criteria fit the deal: we compare loan to value and rates across those lenders, and shortlist two to five lenders for indicative terms on every Southampton deal. The brief covers all types of properties in scope, from retail and office to hotel, HMO, mixed-use, industrial-warehouse and small-cap logistics, with the lender shortlist calibrated to each property and lease structure. Naming a lender describes the market; it does not mean we have a relationship with it.
Will the rent cover it? Will EBITDA cover it? Try here first.
Drop in your purchase price or current valuation, the LTV you are aiming for, and the loan term you want. Pre-set at 7.5%, the 2026 mid-market interest rate locally for prime owner-occupier and commercial investment mortgages, with the slider running 6 to 9% across fixed and variable rate commercial mortgages. The output is a clean monthly mortgage repayments number you can put against your rent roll, your EBITDA, or your business cash flow. For ICR or DSCR stress testing on commercial investment mortgage deals, send the rent roll through and we will model lender-by-lender across our range of commercial lenders.
For a quote against live lender appetite, call me on 07595 366094.
Mortgage inputs
Drag the sliders.
Based on Southampton commercial mortgage market
Your estimate
Estimated monthly payment
£9,734
Capital + interest over 15 years.
- Loan amount
- £1,050,000
- Loan-to-value
- 70%
- Annual rate
- 7.5% pa
- Term
- 15 years
- Total interest
- £702,053
- Total payable
- £1,752,053
Indicative only. Actual rate and LTV depend on the asset, your trading history (for owner-occupier) or rental cover (for investment), and live lender appetite. Send your details for a tailored quote.
High-street, challenger and specialist lenders. Eighteen of them on this page.
The Southampton commercial mortgage market spans high-street commercial divisions, challenger banks and specialist lenders for semi-commercial and trading-business deals. We look at the high-street, challenger and specialist lenders whose criteria fit the deal, not three calls to whoever picked up.
Naming a lender describes the market; it does not mean we have a relationship with it. Specialist sectors (CQC-regulated care, hotel EBITDA, dental goodwill, MOT and petrol forecourt) and private credit for larger structured deals sit with further specialist lenders.
NatWest
High street
Lloyds
High street
Barclays
High street
Santander
High street
Allica Bank
Challenger bank
Shawbrook
Challenger bank
Hampshire Trust Bank
Challenger bank
Aldermore
Challenger bank
Cambridge & Counties
Challenger bank
Cynergy Bank
Challenger bank
Paragon Bank
Challenger bank
YBS Commercial
Building society
OakNorth Bank
Specialist bank
InterBay Commercial
Specialist (OSB)
LendInvest
Specialist
Together
Specialist
Recognise Bank
Challenger bank
Handelsbanken
Relationship bank
Twelve Southampton districts, twelve different commercial property profiles.
Loading map...
What’s changing hands in Southampton commercial property.
24+ commercial-relevant planning applications have been submitted across Southampton in the last 12 weeks — change-of-use to Class E, hotel and leisure consents, office facade refurbs, retail conversions. A market-temperature read drawn directly from Southampton City Council’s public planning register.
Updated 2026-05-15
- 26/00182/FUL12/02/2026
68 Commercial Road, Southampton SO15 1GD
Change of use of central retail unit to mixed-use entertainment venue (puzzles experience, bar — Sui Generis) with associated shopfront alterations
SO15 1GD · PendingView on portal → - 26/00183/LBC12/02/2026
68 Commercial Road, Southampton SO15 1GD
Listed building consent for shopfront alterations companion to 26/00182/FUL, central Commercial Road parade
SO15 1GD · PendingView on portal → - 26/00163/FUL08/02/2026
Bevois Valley Road, Southampton SO14 0LB
Retrospective change of use of first floor above independent F&B retail to Class C1 hotel accommodation in the Bevois Valley student-led F&B corridor
SO14 0LB · PendingView on portal → - 26/00205/DIS15/02/2026
Land rear of 104-107 East Street, Southampton SO14 3HH
Discharge of conditions on 16-flat residential-over-commercial scheme approved under 19/00348/FUL adjacent to East Street central retail
SO14 3HH · ApprovedView on portal → - 26/00161/FUL06/02/2026
Bedford Place, Southampton SO15 2DD
Change of ground floor to Class E cafe with extraction flue and shopfront alterations on the Bedford Place independent F&B parade
SO15 2DD · PendingView on portal → - 25/01428/PA5622/11/2025
Above Bar Street, Southampton SO14 7DT
Class E retail to residential (C3) prior approval, 7 dwellings above former CBD retail unit
SO14 7DT · ApprovedView on portal → - 25/01892/FUL18/12/2025
Westquay Shopping Centre, Harbour Parade, Southampton SO15 1QE
Westquay Hammerson anchor unit reconfiguration, new F&B accommodation and tenant mix update in the flagship CBD retail scheme
SO15 1QE · ApprovedView on portal → - 25/01745/FUL04/12/2025
Mayflower Quarter, Western Esplanade, Southampton SO15 1AA
Mayflower Quarter Watermark redevelopment Phase 2, mixed-use waterfront scheme comprising office, leisure, hotel and residential accommodation
SO15 1AA · ApprovedView on portal →
Source: Southampton City Council Public Access planning register. Filtered for Class B/C/E uses, change-of-use to commercial, and trading-business consents. Direct commercial transaction volume (sold prices, charges register) is sourced separately via Companies House MR01 records and Estates Gazette — ask us for a deal-specific market view.
Typical Southampton commercial mortgage scenarios: how these deals are usually structured.
Adanac Park M271 logistics refinance
Owner-occupier warehouse refinance, SO16, 20 year term
Up to 65 to 70% LTV, challenger bank or specialist lender
Illustrative example: not a completed transaction
Highfield student HMO portfolio refinance
Licensed HMO portfolio consolidated into one facility, SO17, 25 year term
Up to 70 to 75% LTV, specialist lender
Illustrative example: not a completed transaction
Ocean Village marina hospitality acquisition
Trading-business hospitality freehold, SO14, 20 year term
Up to 60 to 70% LTV, specialist lender
Illustrative example: not a completed transaction
The person behind the advice.
Hi, I'm Matt Lenzie. I've spent 25 years in financial services, raising debt and equity, and arranged around £400m of property finance. What I do now is simple: I package each deal the way a credit officer wants to read it, take it to the lenders whose criteria fit, and I don't waste anyone's time if the numbers don't work. If you want a straight answer on your Southampton commercial mortgage, send the deal through. You'll hear back within 48 hours, and it won't be a form response.
Matt Lenzie/Founder · 25 years in financial services
Experience
25 yrs
Financial services, raising debt and equity.
Arranged
£400m+
Property finance arranged.
Lender market
High street to specialist
We approach the high-street, challenger and specialist lenders whose criteria fit the deal. Naming a lender describes the market; it does not mean we have a relationship with it.
Coverage
Southampton & UK
Specialist focus on commercial mortgages for property investors, owner-occupier businesses and trading operators.
Refinance
An illustrative refinance scenario: a warehouse at Adanac Park off the M271, where the borrower compares terms from their own bank with those from a challenger bank active in logistics, typically up to 65% LTV over a 20-year term, with EBITDA cover modelled before legal work starts.
Illustrative example: not a completed transaction
Portfolio Refinance
An illustrative portfolio refinance scenario: a four-block HMO portfolio in Highfield and Portswood let to students, where lenders are compared on criteria for licensed HMOs, typically up to 70% LTV on a 5-year fix within a 25-year term, subject to rental cover at a stressed rate.
Illustrative example: not a completed transaction
First-Time Freeholder Purchase
An illustrative first-time freeholder scenario: a business buying its marina hospitality unit from the landlord at Ocean Village, where the first step is identifying which types of lender consider a single-site trading business, usually a challenger bank or specialist lender with hospitality appetite.
Illustrative example: not a completed transaction
Commercial mortgage FAQs.
Three to five lenders.
Indicative terms in 48 hours.
Send the property details, the LTV you are aiming for, and a rough sense of the trading position or rental income. We will shortlist three to five commercial lenders, run live appetite, and come back with structured terms covering rate, LTV, term, fees and conditions. If the numbers do not work, you will know inside two business hours and will not have wasted a valuer time.